What Do Weather Shocks Reveal? Realized Temperature Variability and Equity Returns
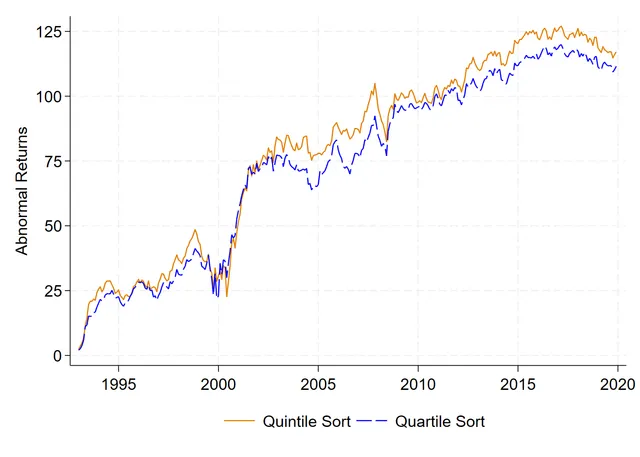
How do U.S. equities respond to abnormal temperature variability — a localized, transitory weather shock with real consequences for firms? Sorting firms each month by realized exposure in their operating states, low-exposure firms outperform high-exposure firms by 4.8% annually. The evidence supports a cash-flow channel that investors find difficult to infer: analyst disagreement rises and earnings surprises are more negative among high-exposure firms.
Best Data-Driven Research Award 2022, Edinburgh Centre for Data, Culture & Society
Abstract
We study how US equities respond to abnormal temperature variability — a localized and transitory shock with significant firm-level consequences. Sorting US firms each month by realized exposure in their operating states, we find that low-exposure firms have contemporaneously greater returns than high-exposure firms, with a return differential of 4.8% annually. Firm-level evidence supports a cash-flow channel, as elevated variability reduces revenues and profits. Consistent with these operating consequences, household spending falls in affected consumer-facing sectors, and workers supply fewer hours. These shocks attract attention as they occur, yet their cash-flow implications are difficult for investors to infer. Analyst disagreement rises and earnings surprises are more negative among high-exposure firms.